Summary
- GrabrFi is a global account, not a traditional bank account: it holds your balance in dollars, gives you an account number in your name, and lets you get paid, save, spend, and cash out to your local currency, all from one app.
- You don't need to be a U.S. resident or travel there. You open the account 100% online with your local ID in minutes.
- It works for both individuals and businesses: freelancers and remote workers use it to get paid by clients and platforms like Upwork, Deel, or Toptal; companies use it to pay their overseas teams and contractors with no fees or forced conversion.
- Because it's a global account and not a bank, your balance isn't treated the same way as a traditional bank deposit, which is worth understanding before deciding how much to keep there.
What is GrabrFi?
GrabrFi is a global account that lets you hold and move dollars without traveling to the United States or being a resident. It combines dollar payments and an international Visa card in one place, built for people who earn, move, and spend across borders.
With just your local ID, you can open an account in minutes, right from your phone. From there, you get an account number in your name that you can use to receive payments as if you were a local, without being one.
It's built especially for people who:
- Work for a company or client abroad, or get paid through platforms like Upwork, Fiverr, Deel, Toptal, or Remote: they want to be paid like a local, even while working from another country.
- Want to protect and grow the value of their money: they save in dollars to avoid losing purchasing power when their local currency devalues, with an account in their name that earns while they're not using it.
- Spend in dollars day to day: they pay for subscriptions or services like AWS, Google Ads, or Adobe, and use their dollars for everyday purchases, regardless of currency.
- Travel often or live between countries: they want one account that follows them across borders, without friction spending in different currencies or depending on a single bank.
Global account vs. bank account: the difference you need to understand
Here's the point that confuses most people new to GrabrFi: a global account is not the same thing as a bank account.
When you open your account, your balance is held in digital dollars instead of as a traditional bank deposit. That comes with real advantages: you can operate 24/7, move your money instantly, and you're not tied to a bank's hours or paperwork.
Stablecoin services are provided through Bridge Building Inc., and more broadly, GrabrFi is backed by a company with the track record of Grabr, which since its founding has been building a product specifically for people who live, work, or get paid in dollars from Latin America.
What can you do with your GrabrFi account?
A quick way to see it:
| Product | What it gives you | Best for |
|---|---|---|
| U.S. account details | An account and routing number in your name, to get paid by ACH or wire | Freelancers, contractors, remote employees |
| Digital dollars | Freelancers, contractors, remote employees | Anyone who gets paid or saves in dollars |
| Boost | Annual rate on your digital dollar balance | Savers |
| Global card | Virtual and physical card, valid anywhere Visa is accepted | Travelers, online shopping, USD subscriptions |
| QR payment | Pay at local merchants straight from your dollar balance | Everyday use in any country where QR payment has been adopted |
| Local currency withdrawal | Cash out to local currency at a competitive exchange rate | Day-to-day expenses in your country |
Now, the detail on each one, and more importantly, why it matters.
Your own U.S. account details
This is the foundation for everything else. With this account, you can receive ACH or wire payments from companies, platforms, and clients anywhere in the world, with no U.S. address or Social Security Number required.
Why you need it: without an account of your own in the U.S., getting paid by an American client or employer usually costs you twice over. A local bank can charge you USD 15–50 just to receive an international wire, and platforms like PayPal or Payoneer take another 2–3% along the way. On top of that, if you can't hold a dollar balance, your bank converts the money immediately, and that's exactly where local banks tend to add a 2–5% margin over the real rate, money you never see.
With your own U.S. account, on the other hand, platforms pay you by ACH (the method they prefer because it's free and fast for them), and you receive the full payment: incoming ACH transfers from companies like Deel, Remote, Toptal, Upwork, or Fiverr cost nothing, and usually clear the same business day.
Digital dollars: your money, available 24/7
Your balance is held in digital dollars, which lets you send and receive money at any hour, any day of the week, with no dependence on banking hours or business days.
Why you need it: traditional bank transfers come with hours, holidays, and multi-day delays. Digital dollars solve that problem at the root: you can move your money at 2 a.m. on a Sunday and it still arrives. For anyone getting paid by clients in different time zones, or who needs to send money on short notice, that constant availability is the difference between solving something today or waiting until Monday.
Boost: put your dollar savings to work
Turn on Boost and your digital dollar balance starts earning an annual rate of 2.65%, with no maintenance fees, no minimum balances, and no lock-ups. You can pull your money out whenever you want.
Why you need it: keeping dollars "sitting still" already protects you from your local currency's devaluation, but it doesn't earn you anything extra. Boost adds a layer of yield to money that was going to sit there anyway, with no need to lift a finger or understand investing. It's the difference between a cushion that only protects you and one that also gives you a push forward.
Global card: spend in dollars anywhere
Get a virtual Visa card instantly, with no opening fee and no maintenance fee, and request the physical card if you need it. It's issued in the U.S. and works anywhere Visa is accepted.
Why you need it: paying with a local card abroad (or on foreign sites like AWS, Google Ads, or Adobe) almost always means a currency conversion with an added margin, and in several Latin American countries, specific taxes on spending in foreign currency on top of that. Paying directly in dollars with your global card avoids that double friction: since the charge comes straight from your dollar balance, it never goes through your card's exchange rate or your local bank's spread. No forced conversion, and no "spending abroad" taxes when you're really just paying in the currency your balance is already in.
QR payment: your dollars, spent like pesos, reais, or soles
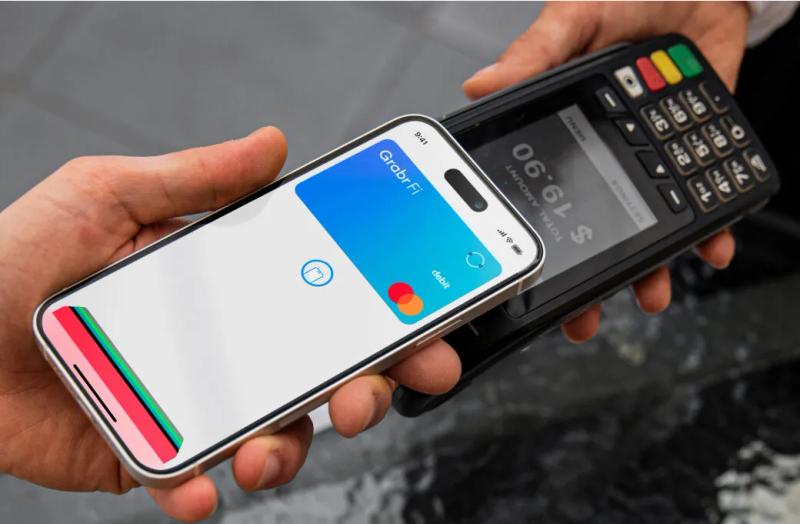
In Argentina, Brazil, and Peru, you can scan a merchant's QR code and pay directly from your dollar balance, with a competitive exchange rate applied on the spot. You pay the converted amount and nothing more, no cash or card terminal involved.
Why you need it: having dollars saved doesn't help much for everyday life (the supermarket, a coffee, the corner store) if you have to convert them yourself first. QR payment gives those dollars immediate, everyday use, without the extra step of converting them on your own.
Local currency withdrawal: the way out when you need it
When you'd rather have pesos, reais, or your local currency in hand (to pay rent, pay someone who works for you, or cover any expense that doesn't take dollars), you can withdraw to your local account at a competitive exchange rate, whenever you want.
Why you need it: not everything is paid in dollars, and an account that only lets you "in" but not easily "out" ends up being a cage. Local currency withdrawal closes the loop: you get paid in dollars, you save in dollars, but when you need local currency, you have it, without depending on a third party or an unfavorable conversion.
Who is GrabrFi for?
- Freelancers: get paid in dollars directly to your account, with no middleman fees eating into each payment.
- Remote workers: receive your full salary from Deel, Remote, or similar platforms.
- Savers: keep your money in digital dollars so it doesn't lose value as your local currency devalues.
- Digital nomads and frequent travelers: global money, local life. Pay with your card, by QR, and withdraw to your local account whenever you want, without depending on one country or bank.
- Everyday spenders: use your dollars for what you buy every day. They work in your neighborhood, in your city, wherever you live.
GrabrFi for businesses: paying global teams without friction
GrabrFi isn't just a product for individuals. More and more companies use it to pay their remote teams, freelancers, and contractors in different countries, without the fees or delays of a traditional international transfer.
The logic is the same as on the user side: since each person has their own U.S. account and routing number, a company can pay them by ACH exactly as it would an employee inside the United States. That cuts both the cost of international transfers and the wait time, and the employee or contractor receives the full payment, with no middleman taking a cut along the way.
Who's behind GrabrFi?
GrabrFi didn't come out of nowhere. It's a product from Grabr, Inc., the company Daria Rebenok and Artem Fedyaev founded in San Francisco in 2015, originally a platform connecting buyers with travelers to bring hard-to-find products across borders. For Grabr, the founding pair were named to Forbes 30 Under 30 (Consumer Technology category) in 2019.
After years of helping their community move products across borders, they noticed a parallel problem: many of those same people struggled to get paid and move money between countries. That's how GrabrFi was born in 2021, as an extension of Grabr focused specifically on solving that financial problem.
GrabrFi is backed by investors including Wayra, Telefónica's open innovation fund, which joined a round led by Gokul Rajaram (a board member at Pinterest, DoorDash, and Coinbase), alongside Tusk Venture Partners and other funds like Cambrian Ventures and Galdana Ventures.
Your global account is also backed by Bridge, a fintech company that manages the assets behind your digital dollar balance. Unlike a bank deposit, these assets aren't FDIC-insured, but their value is backed 1:1 by U.S. dollars and short-term U.S. Treasury bonds.
Today, GrabrFi is available in more than 25 countries and used by more than 250,000 people, with thousands of five-star reviews on Trustpilot and human support in English, Spanish, and Portuguese.
Sin Vueltas: GrabrFi's podcast about real money
GrabrFi also has its own podcast, Sin Vueltas, available on Spotify and YouTube. Each week it brings on guests (freelancers who get paid in dollars, entrepreneurs, crypto experts) to talk about money directly, without jargon.
Topics it covers include:
- Personal finance (budgets, saving habits)
- International freelancing (getting paid in dollars, taxes)
- Crypto and stablecoins
- Global economy
- Entrepreneurship
- Living without borders (digital nomadism, finances while traveling)
Is GrabrFi safe and reliable?
GrabrFi is operated by Grabr Inc., a U.S. company running since 2015, backed by Silicon Valley investors. Your global account is also backed by Bridge, the fintech company that manages the assets behind your digital dollar balance. More than 250,000 people use it worldwide today, with thousands of five-star reviews on Trustpilot, plus human support in English, Spanish, and Portuguese.
That said, as covered above, a global account is not a bank account: your balance is held in digital dollars, not as a deposit, so the same FDIC insurance that would apply to a traditional bank account doesn't apply here. It's worth reading the details in the Help Center article before deciding how much to keep there long-term.
How much does it cost to use GrabrFi?
- Free to open
- No monthly maintenance fee
- No minimum balance required
- Free virtual card issuance
- Free incoming ACH (receiving payments from employers, clients, or platforms)
- Specific fees for international wire/SWIFT transfers and same-day outgoing ACH
For the full, up-to-date breakdown, you can always visit our Help Center.
Frequently asked questions
Is GrabrFi a bank?
No. GrabrFi is a financial technology company (fintech), not a bank. It gives you a global account where your balance is held in digital dollars, with access to a U.S. account and routing number.
Do I need to be a U.S. resident to open an account?
No. You only need your local ID. You can open the account 100% online, without traveling and without being a U.S. resident.
Is GrabrFi insured by the FDIC?
Your balance is held as digital dollars, not as a bank deposit, so FDIC insurance doesn't apply the same way it would to a traditional bank account.
How do I receive payments from Upwork, Deel, or Fiverr on GrabrFi?
You share your U.S. account and routing number with the platform or client when setting up your payment method, and you receive the payment by ACH directly to your account, with no entry fee.
Can I withdraw my balance to my local currency?
Yes. You can withdraw to pesos, reais, or your own local currency at a competitive exchange rate, in the countries where this feature is available.
Can GrabrFi be used by my company to pay a remote team or contractors?
Yes. Each person has their own U.S. account and routing number, which lets a company pay by ACH just like it would an employee inside the United States, cutting costs and time versus a traditional international transfer.
In which countries is GrabrFi available?
GrabrFi is available in more than a dozen countries across LATAM and other regions. The full, up-to-date list is in the Help Center.